
On March 26, 2026, Bill C-15 the Budget 2025 Implementation Act — received Royal Assent. Buried inside that omnibus legislation, alongside a renewed open banking framework, was something the Canadian crypto industry had been waiting years for: a dedicated federal law for stablecoins.
It’s now called the Stablecoin Act (Canada), S.C. 2026, c. 3, s. 600. It’s the first time Canada has given any specific type of crypto asset its own federal statute. And it arrived on the same day that Bill C-12 also received Royal Assent, handing FINTRAC significantly higher enforcement powers and penalty ceilings. March 26 was a busy day in Ottawa.
The law isn’t fully active yet. It needs Governor in Council orders and regulations from the Department of Finance before it comes into force — expected sometime in 2027. But the direction is set, the obligations are written, and anyone issuing or planning to issue fiat-backed stablecoins in Canada now has a federal rulebook to build toward.
What the Stablecoin Act Actually Requires
Four core obligations sit at the centre of the Act.
Registration with the Bank of Canada. Any entity that creates a fiat-backed stablecoin and makes it available to Canadians — directly or indirectly — must register with the Bank of Canada. This applies to non-financial institution issuers. Banks and credit unions already regulated under the Bank Act are excluded from this specific registration track, though they’re not free from stablecoin-related oversight entirely.
1:1 reserve backing. Every stablecoin must be backed at par by high-quality liquid assets in the referenced currency. Those reserves have to be held by a qualified custodian, kept segregated from the issuer’s operating funds, and protected from creditors — meaning if the issuer goes under, holders can still reach the reserves. That last point is not a small detail. It’s the structural lesson drawn from the TerraUSD collapse in 2022 and from several exchange failures since.
At-par redemption on demand. Holders must be able to redeem their stablecoins for the referenced fiat currency at face value, on request. No gates, no queues that conveniently open only when the issuer wants them to.
No yield to holders. Stablecoin issuers are prohibited from paying interest or yield directly to holders. This is a firm line — and one that deliberately puts Canadian stablecoin rules on the conservative end of the global spectrum. The US GENIUS Act, signed into law last July, takes a similar position on yield at the federal level, though the debate there is more contested.
Beyond those four, issuers must maintain governance frameworks, data security standards, financial health disclosures, and recovery and resolution plans. The Act also imposes AML and counter-terrorism financing obligations consistent with existing FINTRAC requirements.
Stablecoin Act: Core Requirements at a Glance
Register with the Bank of Canada (non-financial institution issuers only)
Hold 1:1 reserves in liquid assets, segregated by a qualified custodian
Redeem at par on demand — no gates or delays
No interest or yield paid to stablecoin holders
Governance, risk management, and recovery plans required
AML/ATF obligations consistent with FINTRAC rules
In force: Not yet — Governor in Council orders required, expected 2027
Who It Applies To and Who It Doesn’t
Scope matters here, and it’s worth being precise about what the Act covers.
It applies to fiat-referenced stablecoins – coins pegged to a sovereign currency, most commonly the US dollar or Canadian dollar — that are made available to Canadians with interprovincial or international reach. Closed-loop tokens that operate within a single platform and never circulate broadly are generally outside the scope. So are stablecoins issued by banks and credit unions already regulated under federal banking legislation, though those institutions aren’t operating without oversight either.
Foreign issuers aren’t off the hook. If a stablecoin is accessible to Canadians, the Act applies regardless of where the issuer is incorporated. That’s a significant jurisdictional reach and one that’s consistent with how FINTRAC has always approached its MSB registration requirements — location of operation, not location of incorporation, is what triggers Canadian regulatory obligations.
USDC is currently the only stablecoin that CIRO has designated as an “Approved Stablecoin” under its own terms and conditions for stablecoin margin treatment. That status was established through a separate CIRO pilot in March 2026, allowing registered crypto trading platforms to apply margin rates of 15% to 30% on USDC inventory positions. It’s a more conservative treatment than the 2% capital charge the SEC and CFTC have endorsed in the US — but for Canada, it’s a meaningful step toward treating USDC as a legitimate financial instrument rather than a speculative asset.
CIRO’s Custody Framework: The Other Major Change
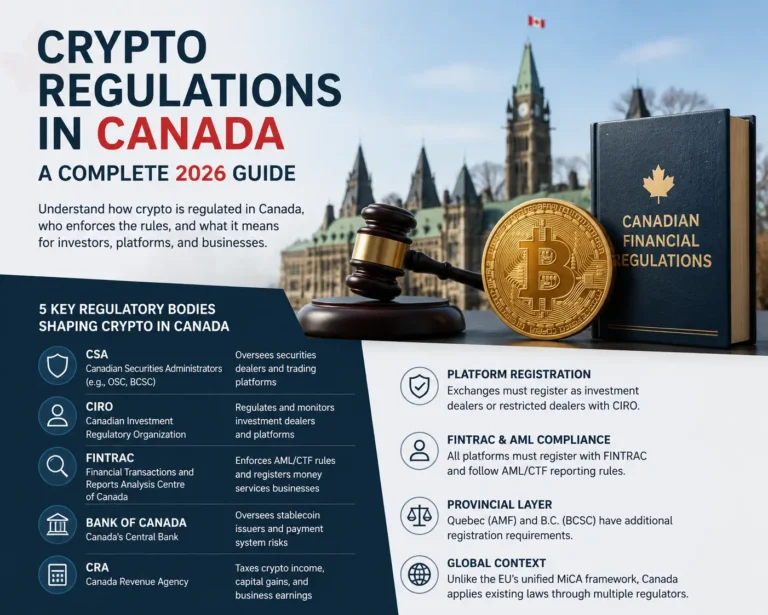
The Stablecoin Act didn’t arrive in isolation. Six weeks earlier, on February 3, CIRO published its Digital Asset Custody Framework — new rules governing how registered investment dealers hold crypto assets on behalf of clients.
The framework bans single-key custody outright. Under the old approach, one cryptographic key could control all client assets on a platform — a structure that created catastrophic single points of failure, as Canadians learned the hard way with QuadrigaCX. CIRO’s rules now require segregated wallets, stronger key management controls, tiered risk-based custody structures, and formal cybersecurity governance. Registered platforms must explain clearly to clients how their assets are held and bear responsibility if funds go missing due to custody failures.
CIRO says it will update the framework proactively as new custody and cyber risks emerge. That’s a somewhat unusual commitment for a regulator, but it reflects genuine awareness that crypto custody risk evolves faster than standard regulatory update cycles can keep pace with. The framework currently operates through terms and conditions of CIRO membership rather than as a formal rule under the CIRO rulebook — a permanent rule is still pending.
FINTRAC’s New Enforcement Teeth
Bill C-12, which received Royal Assent alongside C-15 on March 26, isn’t stablecoin-specific. But it matters for anyone in the Canadian crypto space, because it gave FINTRAC substantially higher maximum penalties and broader enforcement authority under the Proceeds of Crime (Money Laundering) and Terrorist Financing Act.
FINTRAC has already put those tools to use. In 2026 so far, 50 MSB licences have been revoked — 47 of them tied to crypto businesses. Cryptomus was fined $126 million. KuCoin was fined $14 million. These aren’t warning letters. They’re the regulator signalling that the era of provisional tolerance for non-compliant operators is over.
It’s a significant posture shift. For years, FINTRAC’s approach to crypto MSBs was characterised more by registration requirements and periodic audits than by aggressive enforcement. Bill C-12 changed the ceiling for what a penalty could be, and FINTRAC appears to be testing those new limits fairly quickly.
For legitimate registered exchanges and platforms, this is broadly positive — a cleaner competitive environment where non-compliant operators can’t undercut compliant ones by skipping the regulatory overhead. For anyone still operating in a grey area, 2026 is not a comfortable year to be doing so.
OSFI Quietly Raised the Banks’ Crypto Limit Too
One change that received less coverage than it deserved: in Q1 2026, the Office of the Superintendent of Financial Institutions (OSFI) raised Canadian banks’ crypto exposure limit from 2% to 5% of Net Tier 1 capital. That’s a meaningful expansion — it allows federally regulated banks to hold more crypto-related assets on their balance sheets without breaching their prudential limits.
In practical terms, it opens the door for Canadian banks to participate more substantially in digital asset markets, whether through custody services, tokenised products, or direct holdings. Combined with the Bank of Canada’s new stablecoin supervision mandate, it points toward a future where the largest Canadian financial institutions are more meaningfully integrated into the digital asset space — not just offering ETF products as a proxy.
What This Means if You Hold Stablecoins in Canada Right Now
Three things worth understanding if you’re currently holding USDC, USDT, or any other stablecoin on a Canadian platform.
Your holdings are still not insured. The Stablecoin Act doesn’t change this. CDIC protection covers eligible deposits at member institutions. No crypto exchange or stablecoin issuer is a CDIC member, and the Act creates no equivalent insurance mechanism. The reserve and segregation requirements provide structural protection — your coins are backed by liquid assets held separately from the issuer’s operating funds — but that’s not the same as government deposit insurance. If the issuer fails, you’re a creditor with a claim against segregated reserves, not a depositor with automatic protection.
Tax treatment hasn’t changed. The CRA still treats stablecoins as commodities. Every disposal — selling for CAD, trading one stablecoin for another, or spending one on a purchase — is a taxable event. The PARITY Act discussion happening in the US, which would make regulated stablecoin payments tax-neutral, has no equivalent in Canadian law. For a full breakdown of how stablecoin transactions affect your tax position, our Crypto Taxes Canada 2026 guide covers the mechanics.
Full implementation is 12 to 18 months away. The Act received Royal Assent in March but isn’t in force yet. The Department of Finance and the Bank of Canada are developing supporting regulations, which will be published in the Canada Gazette for public consultation before being finalised. Draft regulations aren’t expected before late 2026 at the earliest, with the full framework operational sometime in 2027. If you’re on a registered Canadian platform now, the platform’s existing FINTRAC MSB registration and CSA/CIRO oversight still govern your protection in the interim.
How Canada Compares Internationally
Canada’s framework sits in a reasonable position globally — more coordinated than the US, more conservative than the EU’s MiCA regime on some dimensions, and ahead of most G7 nations in terms of having a dedicated stablecoin statute rather than shoehorning stablecoins into existing securities or banking law.
The US GENIUS Act, signed in July 2025, covers similar ground: federal registration, reserve requirements, redemption rights, and a yield prohibition. The main structural difference is regulator — the US framework distributes oversight between the OCC and state regulators depending on issuer size, while Canada centralises stablecoin supervision in the Bank of Canada. A single federal supervisor creates consistency but also concentrates the rulemaking risk: if the Bank of Canada gets the implementation regulations wrong, there’s no parallel state-level regime to fall back on.
The EU’s MiCA framework, fully in force since December 2024, takes a broadly similar approach on reserves and redemption but allows e-money token issuers to pay a limited form of interest under specific conditions — a flexibility Canada’s Act doesn’t permit. Whether Ottawa revisits the yield prohibition during the consultation process for implementing regulations is one of the more consequential open questions in Canadian crypto policy right now.
Canada’s Stablecoin Act vs. Global Peers
- US GENIUS Act: Similar reserve and redemption rules. Canada uses a single supervisor (Bank of Canada); US splits oversight between OCC and state regulators by issuer size.
- EU MiCA: Both require 1:1 reserves and at-par redemption. MiCA permits limited interest on e-money tokens; Canada’s Act prohibits yield to holders outright.
- UK: UK stablecoin rules are still in development. Canada is ahead on having a dedicated federal statute.
The Short Version
- Canada’s Stablecoin Act received Royal Assent on March 26, 2026, as Division 45 of Bill C-15. It’s the country’s first dedicated federal statute for any crypto asset class.
- Four core requirements: Bank of Canada registration, 1:1 liquid reserves held in segregated custody, at-par redemption on demand, and a hard prohibition on yield to holders.
- Not in force yet. Implementing regulations are expected by 2027. The Department of Finance and Bank of Canada are developing the framework through public consultation.
- CIRO’s custody framework (February 3, 2026) bans single-key custody and requires segregated wallets and tiered risk-based controls for all registered crypto trading platforms.
- FINTRAC pulled 47 crypto MSB licences in 2026 and levied record fines — $126M against Cryptomus, $14M against KuCoin — using new enforcement powers from Bill C-12, which received Royal Assent the same day as C-15.
- OSFI raised banks’ crypto exposure limit from 2% to 5% of Net Tier 1 capital in Q1 2026, opening the door for greater institutional participation in digital assets.
- For stablecoin holders: your coins are still not CDIC-insured, tax treatment is unchanged, and platform oversight in the interim still runs through FINTRAC and CSA/CIRO registration.